Creating a Legacy: How to Make Your Wealth Matter Beyond You
Creating a Legacy: How to Make Your Wealth Matter Beyond You all-my-manage-ui-ment December 26, 2025 Edit Template At some point, financial success becomes about more than lifestyle — it becomes about impact. Why Legacy Matters A clear legacy plan ensures your wealth continues to reflect your values — supporting people and causes that matter long after you’re gone. Ways to Build Your Legacy Philanthropic Giving: Private foundations or sub-funds can create lasting impact and tax benefits. Family Values Statements: Document what matters to you — charity, education, entrepreneurship — so future generations understand your intent. Structured Gifting: Gradual transfers with education attached encourage responsibility. Tax-Smart Philanthropy Australia offers attractive incentives for structured giving, such as Private Ancillary Funds (PAFs) or Public Foundations. These vehicles can create multi-generational impact while reducing taxable income today. In Closing Legacy isn’t about wealth size — it’s about purpose and continuity. “Money can build more than comfort. It can build contribution.”
How to Talk to Your Children About Wealth — Without Creating Entitlement
How to Talk to Your Children About Wealth — Without Creating Entitlement all-my-manage-ui-ment December 26, 2025 Edit Template Passing on wealth is easy.Passing on values is the real challenge. The Risk of Silence Avoiding the “money conversation” often creates confusion or resentment later. Children might not understand how the family’s wealth was earned or why it’s managed a certain way. Age-Appropriate Transparency Young children: talk about saving, giving, and gratitude. Teens: involve them in budgeting or small investments. Adults: share your intentions for family wealth and philanthropy. Teaching Stewardship, Not Spending Encourage responsibility: understanding compounding, risk, and charity. Consider involving them in structured giving or investment discussions. In Closing Wealth can empower or entitle — it depends on the education that comes with it. “The best inheritance isn’t money. It’s mindset.”
The Hidden Dangers of DIY Investing
The Hidden Dangers of DIY Investing all-my-manage-ui-ment December 26, 2025 Edit Template Technology has made investing easier than ever — but not necessarily smarter.Many newly wealthy clients try to manage their own portfolios, thinking, “I’ll just use an app or buy what’s trending.” The Problem with Going It Alone Without a framework, decisions become emotional. Overconfidence during bull markets. Panic-selling when markets fall. Ignoring diversification or tax efficiency. Even professionals diversify because no one predicts markets perfectly. The “Hidden Costs” of DIY Tax drag from frequent trading. Concentration risk from owning too few assets. Opportunity cost from sitting in cash. The Value of Professional Structure An adviser doesn’t just pick investments — they build discipline, objectivity, and accountability into your strategy. DIY can work for small portfolios. But once wealth becomes substantial, structure beats spontaneity.
How to Align Your Wealth with Your Life Goals
How to Align Your Wealth with Your Life Goals all-my-manage-ui-ment December 26, 2025 Edit Template Wealth without direction can feel strangely empty.True financial success isn’t about the balance sheet — it’s about the freedom to live intentionally. Start with Purpose, Not Products Before thinking about investments, define what “enough” means to you. What kind of lifestyle do I want now? What would give me peace of mind in 10 years? Who and what do I want my wealth to support? Translate Goals into Strategy Once purpose is clear, strategy becomes simple: Short-term: maintain liquidity and security. Medium-term: generate reliable income. Long-term: grow and protect legacy wealth. A good plan balances all three. Stay Flexible Life changes. So should your plan.Regular reviews ensure your investments, risk profile, and cash flow stay aligned to evolving goals. In Closing “Money should serve your life — not the other way around.”
How to Build Financial Confidence After Divorce
How to Build Financial Confidence After Divorce all-my-manage-ui-ment December 26, 2025 Edit Template Divorce changes everything — emotionally, legally, and financially.It’s one of the biggest life transitions anyone can experience, and it often leaves new wealth holders feeling cautious, uncertain, and alone. Step 1: Pause and Re-stabilise After settlement, resist the urge to “get everything sorted” immediately. Take a few months to breathe and re-establish daily routines before making big money moves. Step 2: Know Where You Stand Collect and organise: Bank and investment accounts Superannuation balances Property values and liabilities Updated estate documents This clarity replaces anxiety with control. Step 3: Re-design Your Financial Life You now have a clean slate.Ask yourself what you want life to look like — lifestyle, work, housing, future goals.A personalised financial plan can translate those answers into a practical roadmap. Step 4: Learn and Partner Up Many clients say, “I never handled the money before — now it’s all on me.”That’s exactly where a good adviser helps: explaining things in plain English, teaching you what matters, and ensuring you feel informed, not dependent. Step 5: Rebuild with Purpose Divorce can become a powerful reset. It’s your chance to create independence, confidence, and alignment between your money and your new life. “You don’t need to know everything — just the next right step.”
The Estate Plan Most Australians Don’t Have — and Why It Matters
The Estate Plan Most Australians Don’t Have — and Why It Matters all-my-manage-ui-ment December 26, 2025 Edit Template When most people hear “estate planning,” they think of a will.But a will is only one piece of the puzzle — and often the weakest link. In Australia, over half of adults don’t have a current, valid will. Among those who do, many have never reviewed it after major life changes like divorce, new children, or inheritance. The result? Confusion, delays, and sometimes heartbreaking disputes that drain the estate. Why a Will Isn’t Enough A will directs who gets what, but it doesn’t control how or when they receive it. Nor does it protect against tax, divorce of beneficiaries, or creditors. For example, if your adult child inherits a lump sum and later divorces, half that inheritance could end up elsewhere. A testamentary trust (a trust created under your will) can prevent that and distribute income more tax-effectively to dependants. The Key Components of a Complete Estate Plan Updated Will – clear, current, legally valid. Enduring Power of Attorney – someone you trust to act if you can’t. Testamentary or Family Trusts – flexible, protective vehicles for wealth transfer. Superannuation Beneficiary Nomination – often forgotten but can bypass your will. Insurance & Liabilities Review – ensures liquidity for tax or debts. Common Mistakes Assuming your super automatically follows your will. Failing to plan for blended families or step-children. Not communicating your intentions to heirs. In Closing Your estate plan isn’t about dying — it’s about caring for those you leave behind.Ask yourself: “If something happened to me tomorrow, would my family know exactly what to do?” If you’re not sure, it’s time to update your plan.
How to Protect Your Wealth from the Unexpected
How to Protect Your Wealth from the Unexpected all-my-manage-ui-ment December 26, 2025 Edit Template When you’ve recently come into significant wealth — whether through divorce, inheritance, or the sale of a business — your focus is usually on what to do with the money.But one of the smartest first steps isn’t about growth at all.It’s about protection. Wealth creates opportunity, but it also attracts risk — legal, financial, even relational.Protecting your assets is like insuring your lifestyle. You hope you’ll never need it, but you’ll be grateful it’s there if life takes a turn. Here’s how to think about safeguarding your wealth in simple, practical terms. 1️⃣ Understand Where You’re Exposed Most people are surprised when they map out their financial “vulnerabilities.” Ask yourself a few key questions: If I were sued or faced a legal claim, what assets are in my personal name? Would a former partner, creditor, or business associate have any claim on my assets? If something happened to me, would my family easily access what I own? Identifying these potential weak spots is the foundation of asset protection. It’s not about being secretive — it’s about being strategic. 2️⃣ Use the Right Ownership Structures The name on your bank account or property title can make a huge difference to how protected your wealth really is. Some common structures include: Personal ownership – simplest, but highest risk exposure. Joint ownership – can protect against some risks, but still leaves exposure if one party is sued or dies. Family trusts – offer flexibility and can shield assets from legal claims while distributing income tax-efficiently. Companies – can isolate risk from personal assets but don’t always suit personal investments. The right choice depends on your family, goals, and potential liabilities. What matters is that each structure has a clear purpose — protection, tax efficiency, or estate planning — not just convenience. 3️⃣ Protect Your Income, Not Just Your Assets When people think “asset protection,” they often imagine legal structures. But protecting your income is just as important. If you lost the ability to earn or suffered a major illness, how would your financial plan continue?That’s where insurance becomes your financial safety net: Income Protection: Replaces part of your income if you can’t work. Life Cover: Provides financial stability for loved ones. Total & Permanent Disability (TPD): Covers major life-changing events. Trauma Cover: Offers a lump sum for recovery or treatment. Even with strong investments, the right insurance mix keeps your wealth plan on track if life doesn’t go as planned. 4️⃣ Separate “Living” Money from “Protected” Money Here’s a simple but powerful mindset: Treat your personal spending money and your protected assets as two different worlds. Your everyday accounts can handle bills and lifestyle costs.But your investment and legacy assets — the long-term core of your wealth — should sit behind structures (trusts, superannuation, or companies) that reduce personal exposure. It’s like building firewalls in a house: if one room burns, the whole home doesn’t go up in flames. 5️⃣ Keep Your Estate Plan Current An out-of-date will is one of the easiest ways to undo years of careful planning. If your relationship status, dependants, or asset mix has changed, so must your estate plan. Without an updated will or enduring power of attorney: Assets can be tied up in legal disputes. Unintended people may benefit. Taxes and fees can eat into what’s passed on. Regularly review your estate documents with your lawyer — ideally every 2–3 years, or after any major life change. 6️⃣ Don’t Go It Alone Protecting wealth isn’t about paranoia — it’s about peace of mind.That peace comes from having a team who looks at your whole picture: legal, tax, and financial. A coordinated plan ensures your structures, insurance, and estate all align.Because it’s not just about what you’ve built — it’s about making sure it lasts. In Closing Building wealth takes effort. Protecting it takes foresight.The unexpected will happen at some point — whether it’s market volatility, relationship change, or health challenges. The question isn’t if challenges arise, but how ready you’ll be when they do. So ask yourself today: “If something unexpected happened tomorrow, would my wealth — and my family — be protected?” If the answer isn’t a confident yes, then that’s the perfect place to start.
Avoiding the 5 Most Expensive Tax Mistakes Wealthy Australians Make
Avoiding the 5 Most Expensive Tax Mistakes Wealthy Australians Make all-my-manage-ui-ment December 26, 2025 Edit Template When you suddenly come into money — from a settlement, inheritance, or business sale — your tax position can change overnight.Yet most people don’t realise that until they’ve already made a costly mistake. It’s easy to assume that because you’ve “done your own tax” for years, things will stay the same. But once your wealth grows, so does your exposure to tax traps. Let’s unpack five of the most common (and expensive) mistakes newly wealthy Australians make — and how to avoid them. 1️⃣ Believing “Inheritance Is Always Tax-Free” This is one of the most common myths I hear.While Australia doesn’t have a specific inheritance tax, that doesn’t mean all inherited assets are tax-free. Here’s the catch:If you inherit property, shares, or managed funds, you may inherit their capital gains tax (CGT) history too. When you eventually sell those assets, you could face a large CGT bill — even if you didn’t originally buy them. Example:You inherit an investment property originally bought for $400,000 and worth $900,000 when you receive it. If you later sell it for $1 million, you might pay CGT on a $600,000 gain, not just $100,000. ✅ Tip: Before selling or transferring any inherited assets, speak with a tax professional. A simple structure or timing adjustment can save tens of thousands. 2️⃣ Investing in the Wrong Name or Structure A common misstep after receiving a windfall is putting everything in your personal name “to keep it simple.”Unfortunately, that simplicity can become very expensive later. Different ownership structures — individual, joint, company, or trust — each have unique tax treatments and asset-protection benefits. For example: Trusts can help distribute income more tax-efficiently among family members. Companies can cap tax rates but limit access to capital gains discounts. Personal ownership keeps things straightforward but exposes assets to creditors or future relationships. ✅ Tip: Get advice before you invest. The “right structure” isn’t about complexity — it’s about alignment with your goals, risk profile, and family circumstances. 3️⃣ Forgetting About Capital Gains Tax on Big Purchases or Sales Many people remember income tax but forget CGT.Selling property, shares, or even a business can trigger a large tax bill if not planned properly. The problem is timing — CGT is calculated at the point of sale, not when the money lands in your account.So if you sell multiple assets in the same financial year, you could push yourself into a higher tax bracket unnecessarily. ✅ Tip: Consider spreading asset sales over different financial years or using a trust or superannuation contribution strategy to manage the tax impact. 4️⃣ Overlooking the Tax Impact of Divorce Settlements Divorce settlements can have complex tax consequences that many people (and even some lawyers) miss.Transferring property, superannuation, or investment assets as part of a settlement can trigger CGT or stamp-duty implications if not handled correctly. ✅ Tip: Always involve your adviser and accountant before finalising a financial settlement. With the right structuring and timing, much of that tax can be deferred or reduced. 5️⃣ Not Keeping Enough Cash for Tax Bills After major windfalls or asset sales, it’s easy to feel “cash rich.”But when the tax bill arrives months later, many clients realise they’ve already spent or invested too much of it. It’s not unusual for new clients to be shocked by six-figure tax obligations — especially if they didn’t withhold funds for CGT or additional income tax. ✅ Tip: Treat a portion of any windfall as “not yours” — set aside roughly 25–30 percent in a separate account until your adviser confirms the final amount owed. The Simple Way to Stay Ahead You don’t need to know every tax rule — you just need to know when to ask.A proactive accountant and adviser working together can help you: Forecast and set aside tax liabilities. Choose tax-efficient structures early. Use available offsets, super contributions, and franking credits wisely. Avoid double-taxation through careful timing of transactions. That kind of foresight doesn’t just save money — it gives peace of mind. In Closing Taxes are often the largest cost of managing wealth, yet also the most controllable — if you plan ahead. The real mistake isn’t paying tax; it’s paying more than you needed to. So before you buy, sell, transfer, or invest, pause and ask: “What’s the tax ripple effect of this move?” One smart question today can protect a lifetime of hard-earned wealth tomorrow.
Why Holding Too Much Cash Can Quietly Cost You Thousands Each Year
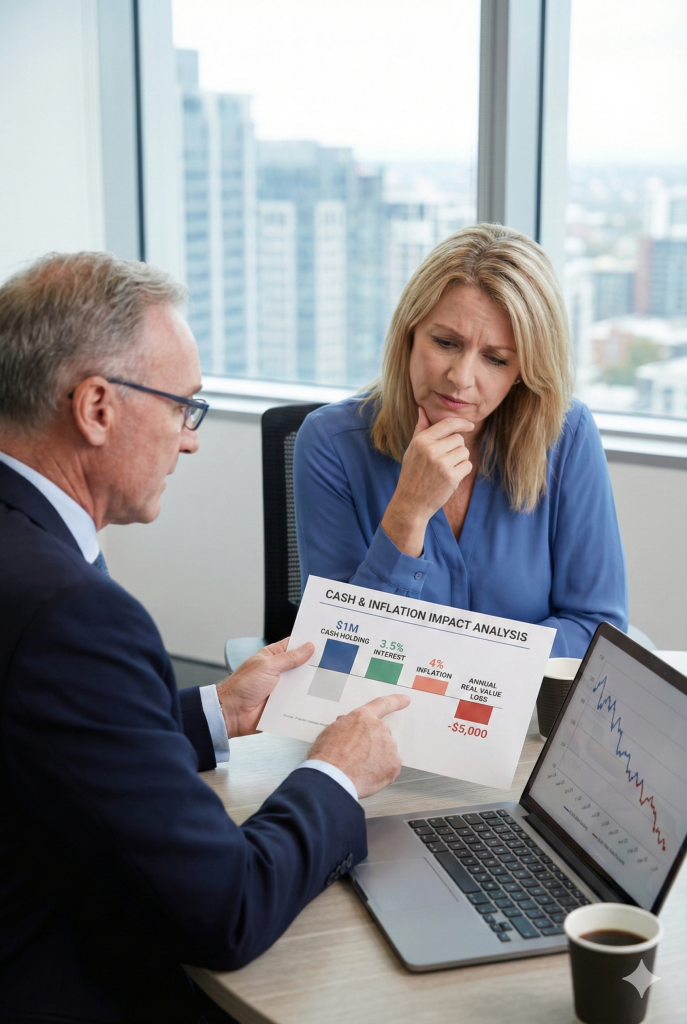
Why Holding Too Much Cash Can Quietly Cost You Thousands Each Year all-my-manage-ui-ment December 26, 2025 Edit Template For many people who’ve recently come into wealth — through divorce, inheritance, or a business sale — the safest option feels like doing nothing.Leaving money in the bank seems calm, sensible, and risk-free. But here’s the truth most people don’t realise: holding too much cash can quietly cost you thousands every year — not through market losses, but through lost opportunity and eroded purchasing power. Let’s unpack why that happens, and how to protect yourself from it. 1. Cash Feels Safe — But Safety Has a Price After major life changes, emotional safety often takes priority over financial return. That’s completely understandable.You might think: “I don’t want to make a mistake. I’ll just leave it in cash for now.” In the short term, that’s perfectly fine — cash gives you breathing room and flexibility.But long term, the safety illusion starts to crack. Imagine this: You hold $1 million in cash earning 3.5% interest, But inflation runs at 4%. In real terms, your money is losing about $5,000 of purchasing power every year — quietly, invisibly. Over a decade, that’s roughly $50,000 gone without a single market crash. Inflation doesn’t send you statements — it just reduces what your money can buy. 2. The Hidden Emotional Cost of Staying in Cash Holding too much cash also creates a subtle form of anxiety.You know you should be investing, but fear of making a wrong move keeps you frozen. Over time, that “decision paralysis” can feel just as stressful as risk itself. As one client once said to me, “I feel like my money’s sitting there doing nothing — and so am I.” It’s not about taking reckless risks — it’s about balancing caution with action. 3. The Balance Between Liquidity and Growth The goal isn’t to abandon cash — it’s to use it intentionally.Think of your wealth as having three “buckets”: Cash & Liquidity (Short-Term) – money for 1–2 years of living expenses and upcoming needs. Income & Stability (Medium-Term) – conservative investments that generate regular returns with lower volatility (like bonds or diversified income funds). Growth & Legacy (Long-Term) – investments aimed at outpacing inflation and building wealth over 5–10+ years (shares, property, managed portfolios). By structuring your money this way, you always have access to funds when you need them — while the rest continues to work for you. 4. Why Diversification Matters More Than Market Timing New investors often wait for the “perfect time” to invest — when markets look calm or interest rates peak. The problem is, markets rarely feel comfortable. The better approach is time in the market, not timing the market.Even gradual entry — investing in stages — can significantly improve outcomes without overwhelming you. Diversification is the key: blending assets that behave differently in various economic conditions helps smooth the ride and reduce regret. 5. How an Adviser Can Add Clarity (and Calm) If you’re not sure where to start, that’s exactly what professional advice is for.A good adviser will: Map out your income needs and time horizons. Stress-test your portfolio against inflation and market scenarios. Ensure your investments align with your personal risk comfort. Most importantly, they’ll help you turn uncertainty into a plan — one that grows your wealth while keeping you at ease. 6. The Real Risk Is Doing Nothing It’s natural to equate “doing nothing” with safety. But in wealth management, inaction can be its own form of risk. By letting inflation quietly eat away at your purchasing power, you might be taking a bigger risk than any diversified portfolio would ever pose. The right balance isn’t about chasing returns — it’s about ensuring your money keeps its real-world value and continues to support your lifestyle. In Closing Cash is important — but it’s not a wealth strategy.It’s a tool, not a plan. Holding some cash gives you flexibility. Holding too much leaves you exposed to the silent drain of inflation. So ask yourself today: “Is my cash giving me security — or just the illusion of it?” If it’s the latter, it might be time to let your money start working as hard as you do.
What to Do First When You Receive a Large Settlement or Inheritance
What to Do First When You Receive a Large Settlement or Inheritance all-my-manage-ui-ment December 25, 2025 Edit Template Receiving a large sum of money — whether from a divorce settlement, inheritance, or business sale — can be both exciting and overwhelming. Many people imagine it will bring instant freedom, yet it often brings confusion and pressure instead. If you’ve recently received significant funds and feel uncertain about your next move, you’re not alone. The truth is: the first decisions you make with newfound wealth often shape your financial future for decades. Let’s talk about what to do (and what not to do) in those crucial early months. 1. Take a Breather Before Making Big Decisions The first step is simple — pause.Emotions run high after major life events like divorce or a family passing. It’s tempting to rush into investments, property, or even “helping” family members. But impulsive decisions can lock in mistakes that are hard to reverse. The wisest first move is to park your funds safely — typically in a high-interest savings or term deposit account — while you take time to think clearly. Even if that money earns only a modest return, it buys you something more valuable: perspective. 2. Get Clear on Your Goals — Before You Touch the Money Wealth is only meaningful when it’s connected to purpose.Ask yourself: What lifestyle do I want to maintain or create? Do I want income stability, long-term growth, or both? Are there dependants or family goals I want to support? Clarity here acts like a compass for every decision that follows. Without it, people often bounce between short-term investments or let money sit idle for years, losing purchasing power to inflation. 3. Build Your “Personal Wealth Team” No one expects you to know all the tax, legal, and investment rules. That’s why assembling a small, trusted advisory team early is crucial. At minimum, your team should include: A financial adviser (to design your overall strategy and cash flow plan) A tax accountant (to optimise structures and avoid surprises) An estate lawyer (to update your will, beneficiaries, and asset protection) Think of this as building a safety net before you walk the tightrope. The right advice pays for itself many times over by avoiding costly errors. 4. Plan Your Spending and Set a Cash Flow System Many newly wealthy individuals underestimate how quickly money can disappear. The key isn’t to restrict — it’s to plan intentionally. A practical system: Allocate 3–6 months of living expenses in cash. Create a short-term bucket (1–3 years of expected spending). Invest the remainder for growth aligned to your goals and comfort level. This “bucket” approach provides stability while your longer-term investments grow in the background. 5. Protect What You’ve Built When your financial situation changes, so does your risk profile. Review insurance (life, income, health) and asset ownership structures. If you now own more than you ever have before, protection becomes non-negotiable. Asset protection isn’t about paranoia — it’s about prudence. It ensures your wealth is safe from unexpected claims, relationship breakdowns, or business risks. 6. Give Yourself Permission to Learn Finally, remember: financial literacy is a journey, not a test.If you’ve never managed large sums before, you’re not “behind.” You’re simply starting a new chapter. A good adviser will explain things in plain English and empower you to make confident, informed choices. In Closing Sudden wealth doesn’t have to be stressful.Handled thoughtfully, it can become a foundation for freedom, security, and purpose.Your first step isn’t to invest — it’s to pause, plan, and surround yourself with the right people. Ask yourself today: “What do I want this money to do for me in 10 years?” The clarity in that answer is where true wealth management begins. Would you like me to proceed with Article #2: “Why Holding Too Much Cash Can Quietly Cost You Thousands Each Year” in the same tone and structure?